.
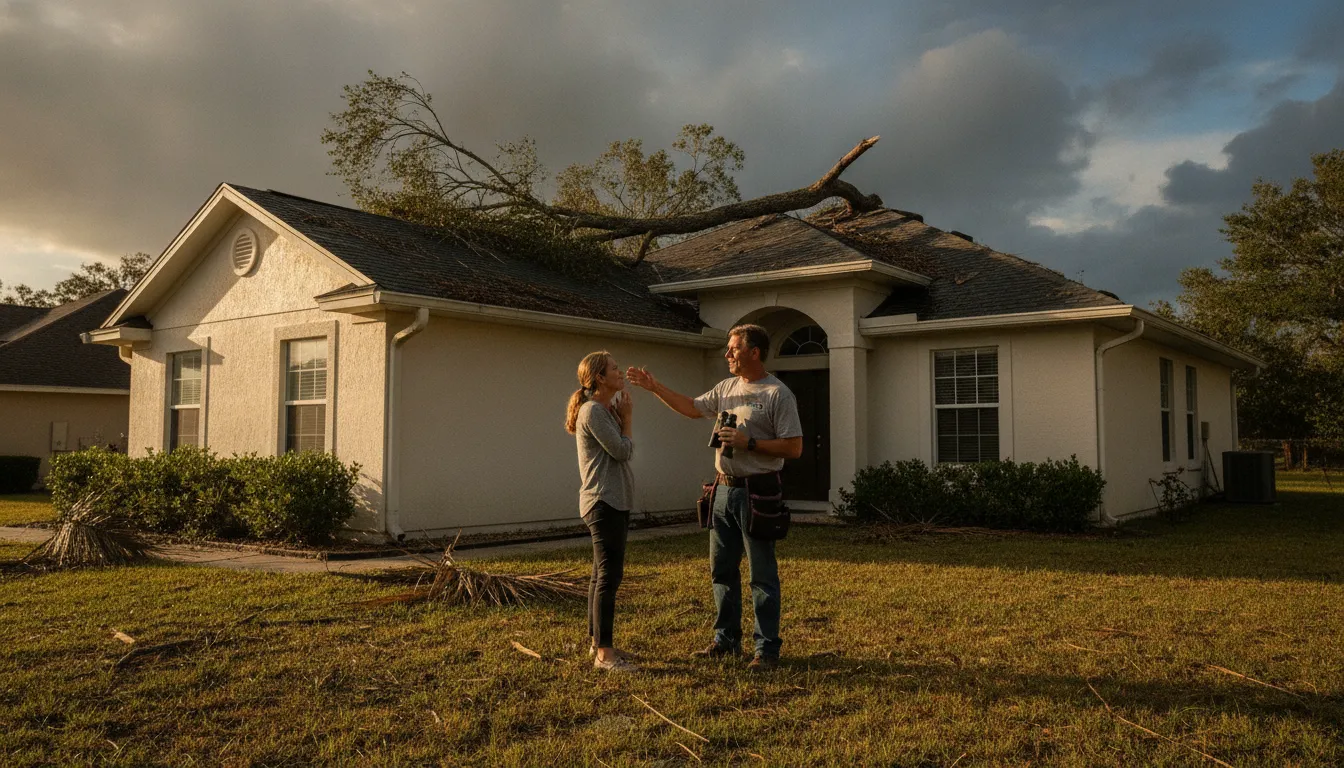
A damaged roof after a Florida storm can leave you wondering whether the next step is calling your insurer, a roofer, or both. The answer depends on more than the age of the roof. Your policy language, the cause and scope of damage, exclusions, deductible, and settlement method all matter.
So, does homeowners insurance cover roof replacement in florida? It may cover covered storm damage, subject to your policy, limits, exclusions, and deductible. Normal wear, deferred maintenance, or an excluded cause may lead to a partial payment or denial. A roofing inspection can document visible conditions, but only your insurer can interpret the policy and decide coverage.
This guide explains what to check, how to document damage, and what questions to ask before filing a claim. If replacement becomes the appropriate repair path, you can also review what to expect during a Florida roof replacement. First, let us separate commonly covered causes from conditions that usually require closer policy review.
Does Homeowners Insurance Cover Roof Replacement in Florida?
Usually, homeowners insurance may cover roof damage when a sudden, covered event causes the loss, such as certain severe weather or fire. The National Association of Insurance Commissioners explains that homeowners policies pay for damage caused by a covered disaster, but the policy controls what qualifies as covered damage. Review your declarations page, exclusions, deductible, and claim requirements before assuming a roof replacement will be paid.
For helpful context on the replacement process itself, see what to expect during a Florida roof replacement. The coverage question and the construction question are related, but they are not the same decision.
What can change the insurance outcome?
Sudden storm damage is different from gradual deterioration. Regular wear and tear, age-related failure, poor maintenance, neglect, and excluded causes are generally less likely to qualify than a documented covered event. Even when a loss is covered, your deductible reduces the payment. And the policy may limit settlement to actual cash value rather than the cost of a new roof.
Some Florida policies or endorsements offer replacement-cost treatment for covered repaired or replaced losses, subject to policy limits and conditions under Florida law. Other policies may contain roof-age, inspection, deductible, or actual-cash-value provisions. Those terms vary, so confirm them with your insurer or a qualified insurance professional. A roofer can inspect and document visible conditions, but cannot guarantee coverage or decide how your policy applies.
When Does Insurance Pay for Full Replacement vs. Repair?
The decision between a roof repair and a full replacement usually starts with the cause and scope of the damage. A sudden covered event, such as certain wind or weather damage, may be treated differently from age, wear, deterioration, or an excluded cause. Your policy language, limits, deductible, and claim facts all matter, so an inspection alone cannot answer whether does homeowners insurance cover roof replacement in Florida for your situation.
What affects the insurance settlement?
| Question | What to review |
|---|---|
| Cause | Was the damage sudden and from a covered event, or from wear, age, neglect, or an exclusion? |
| Payment basis | Does the policy use replacement cost or actual cash value for the covered loss? |
| Out-of-pocket amount | What deductible applies, and are there roof-specific conditions or limits? |
| Scope | Does the insurer’s estimate address the visible damage and required work? |
Settlement method is another important distinction. Florida law requires insurers to offer coverage that adjusts certain repaired or replaced covered losses on a replacement-cost basis rather than actual cash value. Subject to the policy limits and provisions. Replacement cost generally addresses the cost to repair or replace covered damage, while actual cash value accounts for depreciation. The policy may also contain conditions that affect when replacement-cost benefits are paid.
Your deductible reduces the amount available for a covered claim. For smaller losses, the National Association of Insurance Commissioners advises homeowners to check the deductible and consider whether paying for minor repairs themselves makes sense. A contractor can inspect the roof, document visible conditions with photographs, and explain whether the observed damage appears localized or widespread. That documentation can help you discuss the claim, but it does not determine coverage, cause, or the insurer’s final decision.
For background on the construction process and replacement planning, see this guide to what to expect during a Florida roof replacement. Confirm coverage questions, settlement terms, and claim requirements directly with your insurer or a qualified insurance professional.
What Florida’s Roof-Age and 25% Rules Actually Mean
Florida’s roof-age rules address insurance eligibility and renewal. They do not decide whether a specific storm claim will be paid. Under Florida Statute 627.7011, an insurer generally cannot refuse to issue or renew a homeowners policy solely because a residential roof is less than 15 years old. For a roof at least 15 years old. The homeowner must be allowed to obtain an inspection by an authorized inspector before replacement can be required as a condition of issuance or renewal. A qualifying inspection showing at least five years of useful life remaining can also protect against refusal based solely on roof age.
Roof age, ordinance coverage, and the 25% rule are separate questions
The statute calculates roof age from the last date when the full roof surface was built or replaced according to code. It also addresses coverage for costs needed to comply with applicable laws and ordinances. That coverage may be limited to 25% or 50% of the dwelling limit. A dwelling policy is generally deemed to include 25% law-and-ordinance coverage unless the policyholder provides a written refusal. These provisions still depend on the policy’s terms, limits, and exclusions.
The often-mentioned 25% rule is a building-code issue. It limits how much of a roof area or section may be repaired, replaced, or recovered in a 12-month period unless the applicable code requirements are met. See the cited Florida 25% rule explanation. It does not automatically require an insurer to pay for a full replacement. Whether a covered storm loss, code-related work, or replacement cost is payable remains a policy-specific coverage question, not a conclusion a roofer can make.
How to Document Storm Damage Before Filing a Claim
- Report the damage promptly. Contact your insurer or agent as soon as you can. Reporting timelines vary, and many insurers set claim deadlines. Ask what documentation and next steps your policy requires. The NAIC recommends prompt notice, while Florida’s consumer guide also advises immediately reporting the claim.
- Photograph the property before cleanup. From a safe location, take wide and close-up photos or video of visible roof damage, fallen branches, damaged ceilings, walls, floors, and personal property. If you must make an emergency repair first, photograph the condition before and after the work. Florida’s Department of Financial Services recommends keeping receipts for those repairs. Do not climb onto a wet or unstable roof.
- Protect the home from further exposure. Use reasonable temporary measures, such as having a qualified professional cover an opening or place a tarp where needed. Keep every receipt and note what was done. Temporary protection is not the same as authorizing permanent repairs, and reimbursement depends on the policy and covered loss.
- Build a damaged-item inventory. List each affected item with a specific description, approximate age when known, and location. Include photos, videos, purchase records, and receipts for repairs or newly purchased items. Keep copies in a secure location.
- Preserve evidence when practical. Do not discard damaged materials or belongings before the insurer has a reasonable opportunity to inspect them, unless leaving them in place creates a safety risk. Save samples or debris and record the storm date and visible conditions.
- Prepare for the insurer’s inspection. After a loss is reported, the insurer may send an adjuster, use a drone, or hire another expert to evaluate the cause and scope of damage. Be present if possible, provide your records, and request a copy of the written estimate or decision. A roofing contractor can document roof conditions, but cannot decide coverage.
- Check repair provisions before signing. Before entering a repair contract, ask your insurer whether the policy includes managed-repair requirements or preferred vendors. Read the agreement carefully, and do not sign under pressure. The Florida DFS consumer guide recommends confirming these provisions first: review its claim guidance for the process and limitations.
What to Do If Your Insurance Claim Is Denied or Underpaid
A denial or smaller-than-expected payment is not the end of the process, but it is a reason to slow down and review the details. Ask for the insurer’s written decision, itemized estimate, and explanation of the policy language used. Florida’s consumer guidance says you should generally receive a written denial or payment for the undisputed portion within 60 days of reporting a claim, subject to stated exceptions.
Review the scope before deciding what comes next
Compare the insurer’s scope with the damage observed during a qualified roof inspection. Look for omitted roof slopes, flashing, vents, interior water damage, or temporary protection needs. A contractor can document visible conditions and prepare an estimate, but cannot decide whether your policy covers the loss. For a practical overview of documenting weather-related damage, see this storm damage roof repair guide.
If the scope does not match the documented conditions. The Florida Department of Financial Services recommends obtaining estimates from contractors of your choice and submitting them to the insurer for reconsideration. Include photos, measurements, reports, and a clear explanation of each difference. Before signing a repair contract, confirm whether your policy includes managed-repair provisions or preferred vendors. Do not let anyone pressure you into work you do not understand or want.
If you still disagree, ask the Florida Department of Financial Services whether you qualify for its Residential Property Mediation program. The consumer guide identifies it as a no-cost option for eligible disputes. Mediation is not a guarantee of payment. North Wood’s Roofing can provide a straightforward inspection and documentation without pressure or a promise of claim approval.
How a Roofing Contractor Can Help Without Deciding Coverage
A qualified roofing contractor can help you understand the roof’s physical condition and organize useful documentation. That support can make conversations with your insurer more productive. But it does not answer the question, “does homeowners insurance cover roof replacement in Florida?” Coverage depends on your policy. The cause of loss, exclusions, deductible, and the insurer’s review.
What a contractor can document
During an inspection, a roofer can photograph observed damage and note visible signs of wind or weather impact. The roofer can explain whether the roof appears to need a repair or more extensive replacement. The contractor can also prepare a clear scope describing the work, materials, and areas requiring attention. If the roof is actively exposed, the roofer may recommend safe temporary measures to help limit additional damage. Florida consumer guidance also recommends documenting emergency repairs before and after the work and keeping receipts: Florida’s claim guide.
North Wood’s Roofing can provide roof repair and storm-damage services for homeowners in Gainesville, Live Oak, Lake City, and nearby North Florida communities. However, a roofer cannot interpret your policy, act as your adjuster, or guarantee claim approval. The insurer makes the coverage decision. If you disagree with that decision, Florida guidance says you may submit contractor estimates for reconsideration. Before signing repair work, confirm any preferred-vendor or managed-repair requirements with your insurer. You can request a free roof inspection to document the condition and discuss practical next steps without pressure.
Frequently Asked Questions
Can you insure a 20 year old roof in Florida?
Possibly. Roof age can affect eligibility, renewal, inspection requirements, and policy terms, but it does not by itself answer whether a later loss is covered. Florida law addresses certain issuance and renewal decisions for older roofs, including an inspection option in some circumstances. Review your policy and ask your insurer what documentation it requires.
Can I get my roof replaced for free in Florida?
There is no general free-roof replacement program through homeowners insurance. A policy may pay for covered damage after the deductible and subject to its limits, exclusions, and settlement terms. Normal aging, wear, or maintenance issues may not qualify. A contractor can document conditions and prepare repair or replacement options, but the insurer decides coverage.
What is the new law in Florida about roofs?
Florida’s roof-age provisions apply to homeowners policies issued or renewed on or after July 1, 2022. For qualifying roofs at least 15 years old, the law addresses when an insurer may require replacement and allows an authorized inspection in certain situations. It is an insurance eligibility rule, not a promise that storm damage will be paid. Read the Florida statute.
What is the 25% roof replacement rule in Florida?
The 25% rule is often confused with an automatic insurance payment rule. Florida law addresses law-and-ordinance coverage, which may be limited to 25% or 50% of the dwelling limit depending on the policy option. Building-code requirements and claim payment still depend on the applicable code, policy language, covered cause, limits, and deductible. Check the statute and your policy.
Schedule a Free, Honest Roof Inspection
A clear inspection can help you understand your roof’s condition and organize documentation before discussing storm damage with your insurer. North Wood’s Roofing can provide a straightforward assessment without deciding what your policy covers. To request a free, honest roof inspection, contact North Wood’s Roofing.